If you have several debts, it is easy to feel as though every repayment disappears without changing anything. A debt snowball or debt avalanche gives each dollar a job: keep minimum payments going on every debt, then focus all extra money on one balance at a time.
The snowball is built for momentum. The avalanche is built for maths. Both can work. The winning method is the one you will actually stick with.
The basic rule both methods share
First, list each non-mortgage debt: its balance, interest rate, minimum repayment and due date. Continue paying at least the minimum on all of them. Then choose one target debt and put every available extra dollar towards it.
When that debt is cleared, roll its old minimum payment — plus your extra payment — onto the next target. That growing repayment is the “snowball” effect. It also happens with an avalanche; the name simply describes the order you tackle debts.
Do not stop paying other debts while you focus. Missed payments can bring fees, damage your credit record and make an already expensive problem worse.
Debt snowball: smallest balance first
With the snowball, rank debts from smallest balance to largest, ignoring interest rates. Clear the smallest first, then move upward.
Why people like it: you may eliminate an account quickly. One less bill, one less login and one less minimum repayment can make the plan feel real. That emotional lift matters, especially if debt has been hanging over you for months.
The downside is cost. If a large, high-rate credit card sits further down the list, it can keep accumulating expensive interest while you clear cheaper debt first. Average credit card rates are around 20.99% a year, according to RBA data cited in mid-2026 reporting. Canstar also reported about $19.4 billion in Australian card balances accruing interest, with roughly $10 million in interest charged each day.
Debt avalanche: highest interest rate first
With the avalanche, rank debts from highest interest rate to lowest, ignoring balance size. Attack the highest-rate debt first.
This is usually the cheapest route. Every extra dollar reduces the balance that is charging you the most interest, so less interest has time to build. It is particularly powerful for credit cards, payday-style lending and high-rate personal loans.
The downside is psychological. Your first target may be a $7,000 card balance rather than a $300 account. Progress can be harder to see in the first few months, even though the numbers are working in your favour.
Worked example: same debts, different order
Imagine Sam has $450 a month available above minimum repayments. Their debts are:
- Store card: $600 at 24.99%, minimum $30 a month
- Credit card: $3,000 at 20.99%, minimum $90 a month
- Personal loan: $5,000 at 11.99%, minimum $160 a month
- Interest-free retail purchase: $1,200 at 0%, minimum $50 a month
Sam keeps paying all $330 in minimums and adds the $450 extra payment to the chosen target.
Under the snowball, Sam clears the $600 store card first. It may be gone in about two months, creating an early win. Next comes the $1,200 interest-free purchase, then the credit card, then the personal loan. The catch: the 20.99% card remains in the background while Sam clears the 0% balance.
Under the avalanche, Sam targets the store card first too, because it is both the smallest and highest-rate debt. But next they attack the 20.99% credit card, then the 11.99% personal loan, leaving the 0% purchase until last. With the same payments and no new borrowing, this order will generally cost less overall because the high-rate balances shrink earlier.
The exact saving depends on statement timing, minimum-payment rules and whether rates change. But the principle is firm: if you can stay motivated, avalanche is the mathematical winner.
How to choose without overthinking it
Choose the avalanche if you can tolerate slower early milestones, have high-interest card debt, and want to minimise interest.
Choose the snowball if you are overwhelmed, need a quick account closure to stay engaged, or have several very small balances creating admin chaos.
A hybrid is fine too. Clear one tiny nuisance debt — say, a $150 overdue bill — then switch to avalanche. There is no prize for using the purest version of either method.
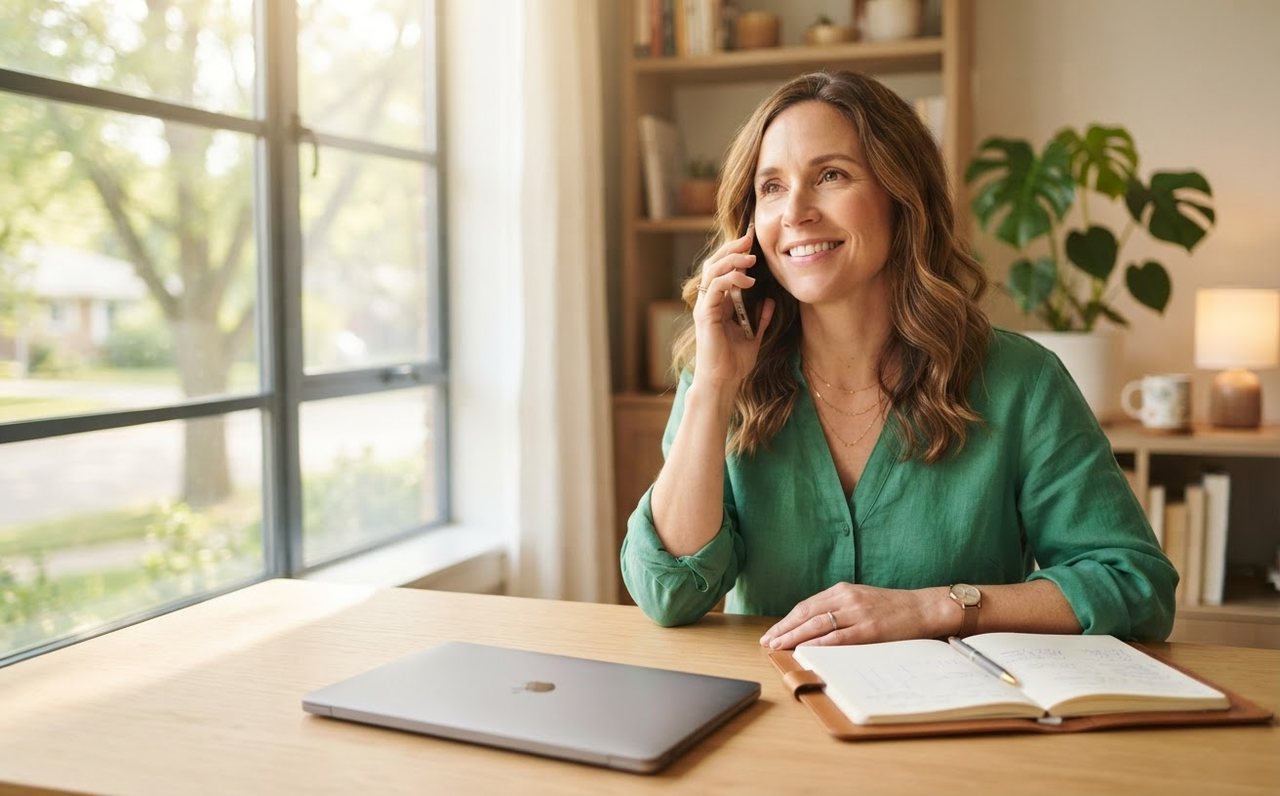
Set up a plan that survives real life
- Stop adding to the pile. Remove saved card details from shopping sites, pause BNPL use and use a debit card or cash for day-to-day spending where possible.
- Find one repeatable extra amount. Start with $20, $50 or $100 per payday. A plan you can maintain beats a heroic amount that collapses next week.
- Automate it after payday. Schedule the target payment for a day or two after income arrives.
- Keep a small buffer. Even $300–$500 set aside can reduce the chance that a tyre, prescription or school cost goes straight back on a card.
- Call lenders early if minimums are tight. Ask about hardship options, lower repayments, a payment arrangement or an interest-rate review. Do this before missing payments if you can.
- Review after every debt disappears. Roll the freed minimum into the next target; do not quietly absorb it into spending.
This matters in a high-cost environment. ABS figures released in August 2026 put annual CPI at 3.5% to July, with housing up 5.0% and food up 3.2%. When rent, mortgage payments and groceries are already stretching income, debt plans need to be practical, not perfect.
You do not need to clear every debt this month to be making progress. Pick an order, protect your minimum payments, send one extra amount consistently, and let each cleared balance make the next one easier.
This article is general information only and not personal financial advice.